Cash Secured Put Calculator | Free Tool & Strategy Guide (2026)
A cash secured put calculator turns a strike, a premium and days to expiration into five numbers: the cash you need, your return on that cash, the annualized return, your breakeven and a rough chance of assignment. Our free cash secured put calculator runs the first four (cash required, return, annualized return, breakeven) on a live premium where one is available. For delta, use the Strategy Analyzer or the scanner. Below are the formulas, one worked example, and what the output doesn't tell you.
Run the numbers now: open the Days to Expiry cash secured put calculator and enter a ticker, capital, days to expiration and your fees per contract.
The five formulas
Selling a put obliges you to buy 100 shares at the strike if you're assigned. "Cash secured" means that money is set aside for the whole trade.
Cash required     = Strike × 100 × Contracts
Premium collected = Premium per share × 100 × Contracts − Fees
Premium return    = Premium collected ÷ Cash required   (= Premium ÷ Strike before fees)
Annualized return = Premium return × 365 ÷ DTE
Breakeven         = Strike − Premium per share
Assignment odds   ≈ |Put delta|
Two return conventions. Premium ÷ strike measures the return on the cash you actually set aside. Premium ÷ (strike − premium) treats the premium as reducing your outlay, so it comes out slightly higher.
Our calculator uses premium ÷ strike, after subtracting fees, and I'd stick with that one. It's the more conservative number, and it matches the cash your broker actually holds.
Annualized is simple, not compounded. The calculator multiplies by 365 ÷ DTE. It doesn't compound, and it assumes you could repeat the same trade at the same return back to back. Treat it as a way to compare trades of different lengths, not as a forecast of your year.
Delta is an approximation. The absolute delta of a put is a rough stand-in for the chance it finishes in the money at expiration. It comes from the option's implied volatility, so it's only as good as that IV, and it says nothing about early assignment.
A worked example (hypothetical)
Say a stock trades at $52. You sell one 30-day $50 put for $1.00 a share, its delta is −0.25, and your broker charges $1 per contract.
| Metric | Arithmetic | Result |
|---|---|---|
| Cash required | $50 × 100 | $5,000 |
| Premium collected | $1.00 × 100 − $1 fee | $99 |
| Premium return | $99 ÷ $5,000 | 1.98% |
| Annualized return | 1.98% × 365 ÷ 30 | 24.1% |
| Breakeven | $50 − $1.00 | $49.00 |
| Buffer below today's price | ($52 − $49) ÷ $52 | 5.8% |
| Assignment odds | |−0.25| | about 25% |
Before fees, the return is $1.00 ÷ $50 = 2.0%, which annualizes to 24.3%.
On the other convention, $1.00 ÷ $49 gives 2.04%. The gap is small at this premium and grows as the premium gets larger relative to the strike.
If you're assigned, you buy 100 shares at $50 but you've kept the premium, so your effective cost is $49 a share. Below $49 at expiration, the trade is losing money.
The 25% is the rough chance you end up owning the shares, so the real question is whether you'd be happy owning this stock at $49.
How our calculator works
On the calculator page, check that the strategy is Cash-Secured Put (the default on that page) and enter your capital, ticker, days to expiration and fees per contract. It then does the following:
- Loads the current stock price and sets the strike 2% below it.
- Looks up a live premium for the nearest listed strike from our put finder, within a week either side of your DTE. The result is tagged Live. If no quote comes back, it falls back to a rough estimate from the IV field and tags it Estimated.
- Works out how many contracts your capital covers (capital ÷ (strike × 100), rounded down) and applies the formulas above to that many contracts.
- Shows monthly income (net premium × 30 ÷ DTE), annual yield, breakeven, and the buffer between today's price and breakeven.
The risk-level buttons set the delta range used when you open the setup in the Strategy Analyzer, which shows the individual strikes.
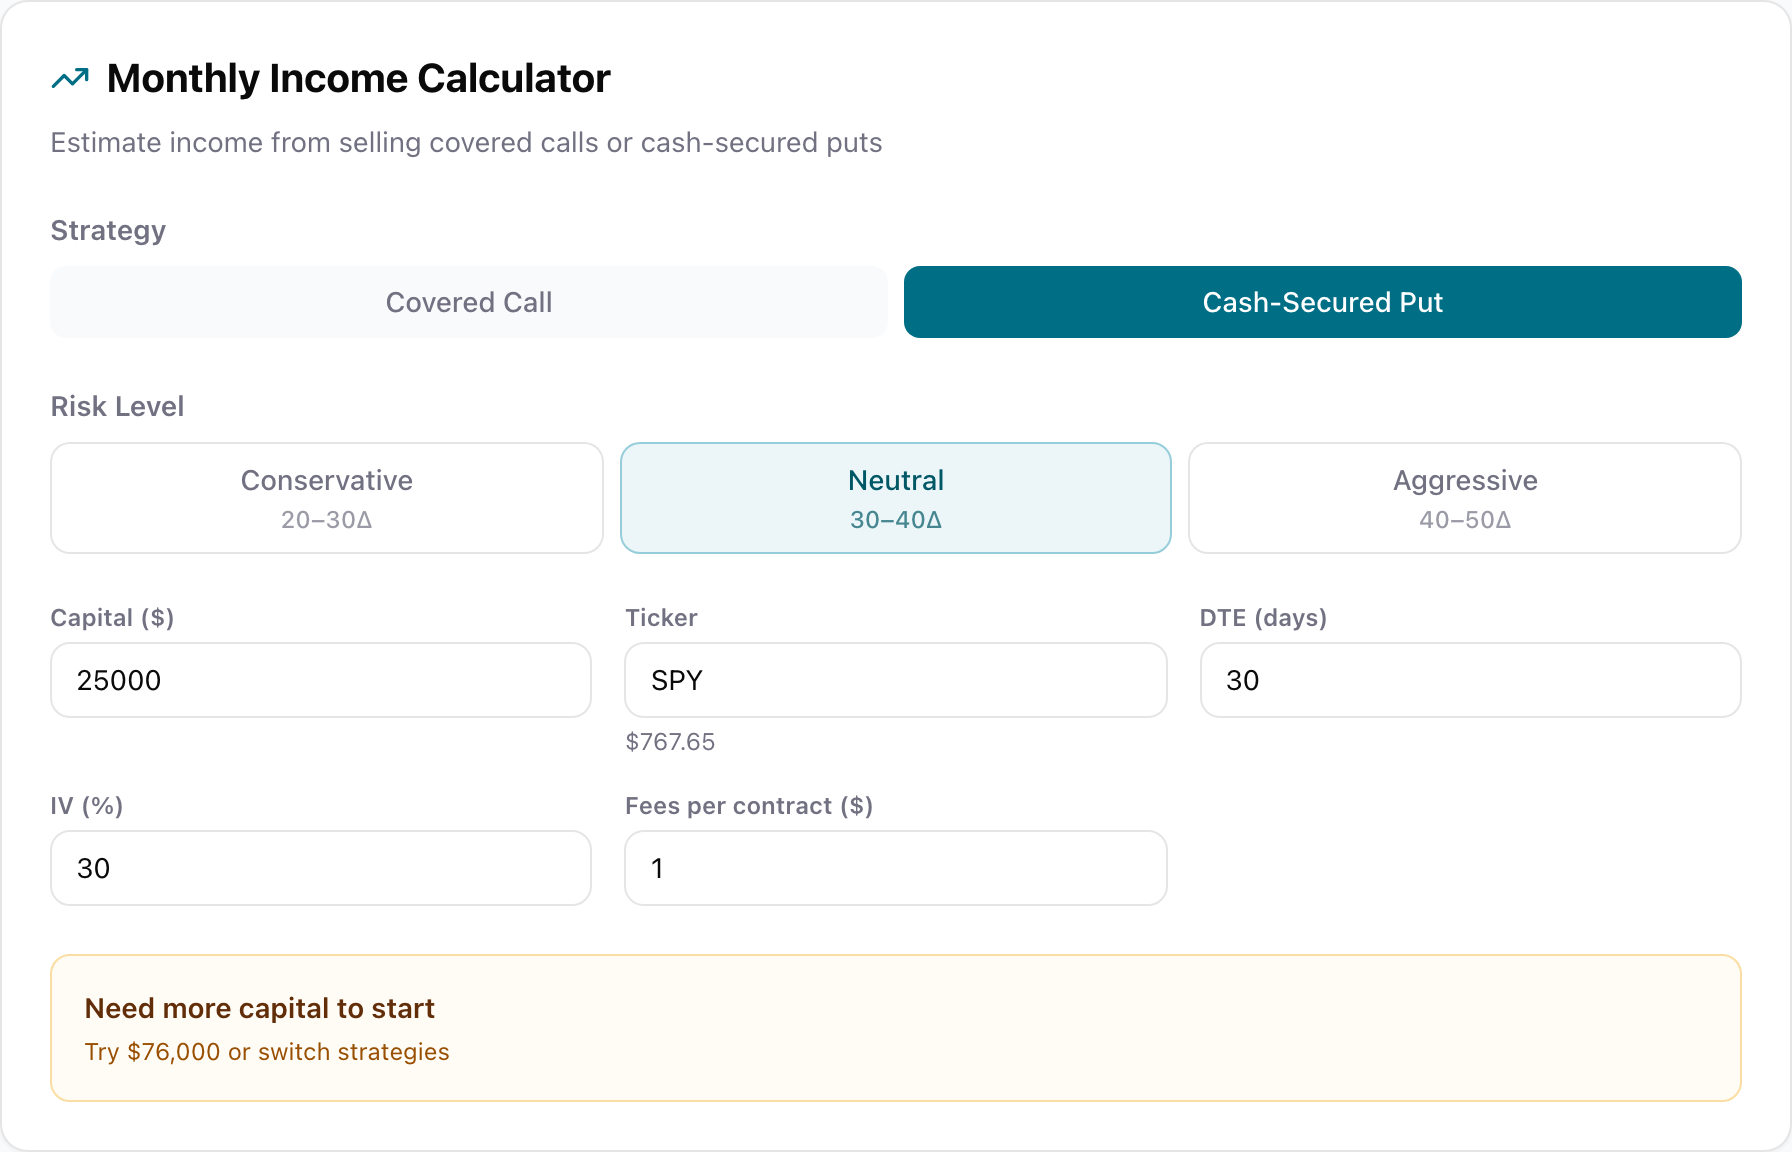 The Days to Expiry cash-secured put calculator with SPY entered and a message asking for more capital
The calculator with its default inputs, captured 24 September 2026. SPY was at $767.65, so a put 2% below that needs about $752.30 × 100 = $75,230 of cash per contract. The default $25,000 doesn't cover one, and the calculator says so instead of showing a return.
That screenshot is the cash-required formula doing its job. On a high-priced ETF, one contract ties up a lot of money.
With less capital, pick a lower-priced stock, or look at a put credit spread, where your risk is capped by the spread width instead of the full strike.
What the calculator can't tell you
Opportunity cost. The cash behind a put could sit in T-bills or a money market fund instead. Your extra return is the put's annualized return minus that yield, and you only earn it by taking on the risk of owning the stock.
The widget below compares the two on fixed assumptions built into it, not live premiums or live T-bill rates, so use it for the shape of the trade-off and the calculator for your actual numbers.
CSP vs T-Bills: Income Comparison
Compare cash-secured put income with T-bills at rates you enter. Both rates are your assumptions, not live market data.
Free account. Re-run this scan with live prices any time.
Assignment ties up your cash. The annualized figure assumes the put expires and you sell another one. If you're assigned and hold the shares for months, your cash earns whatever the stock does.
Plan for that before you sell the put, usually by knowing which covered calls you'd sell next (wheel strategy guide).
Whether the premium is rich or cheap. A $1.00 premium can be high for one stock and low for another. The cash-secured put scanner lets you filter by delta, annualized return and IV percentile across many tickers.
Earnings and dividends. An earnings report before expiration can gap the stock through your strike. Once you own the shares, dividends and ex-dividend dates matter too. Check both calendars before you pick an expiration.
A short routine
- Pick a stock you'd be fine owning, and a breakeven you'd be fine paying.
- Run it through the calculator to see cash required and annualized return after fees.
- Check the put's delta in the Strategy Analyzer or the scanner, and treat it as your rough assignment odds.
- Compare annualized return with what the same cash earns in T-bills.
- Add up the cash required across all your open puts before you sell another one.
Premium ÷ strike, times 365 ÷ DTE, with the breakeven checked against a price you'd actually pay, covers most of the decision.
Related reading
- Options Greeks Explained
- Options Assignment Probability
- Cash-Secured Puts Playbook
- Rolling Cash-Secured Puts
- Best Stocks for Selling Cash-Secured Puts
- Selling Cash-Secured Puts on Thinkorswim
- Options Trading for Beginners
- Covered Call Calculator
- Covered Call Screener Tools
- Free Portfolio Analysis Tool
- Stocks With the Highest Option Premiums: Implied Volatility for 17 Tickers
Frequently Asked Questions
Written by Florian Strauf
Continue Your Journey
Covered Call Analyzer
Find the best covered call opportunities.
Cash-Secured Put Calculator
Calculate put selling returns.
Demo Portfolio
Explore a sample portfolio with positions and strategy insights — no login required.
Wheel Strategy Calculator
Plan your wheel trades.
Free scanner account
Scan free — then add the full workflow
- Live broker sync (33+ supported brokers; daily auto-refresh for IBKR Flex)
- Portfolio Scanner for comprehensive recommendations
- Strategy backtesting for covered calls and puts
- Full wheel backtesting with buy‑and‑hold comparison